15-Year vs. 30-Year Mortgage: Which Is Better?
Is a 15-year mortgage better than a 30-year mortgage? It’s one of the most consequential financial decisions you’ll make — the choice can mean a difference of hundreds of thousands of dollars in interest. The 15-year builds wealth dramatically faster; the 30-year offers flexibility and lower payments. Neither is universally “better” — the right answer depends on your finances, goals, and discipline. Here’s the complete 2026 breakdown.
The Raw Math: What Each Costs
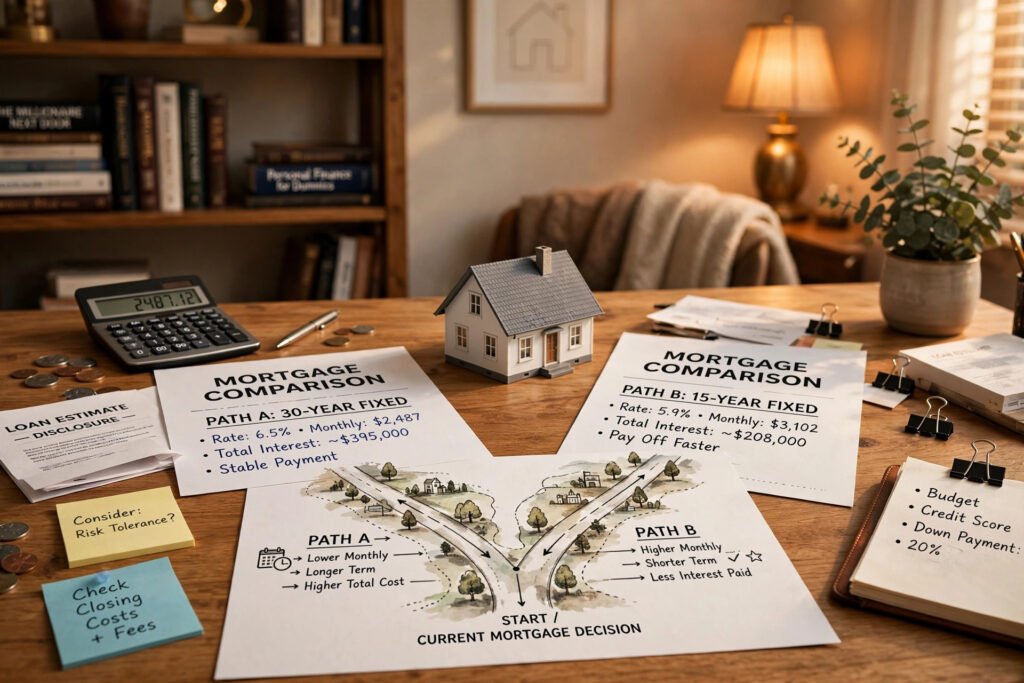
On a $300,000 loan at typical 2026 rates (assume 6.0% for 30-year, 5.5% for 15-year — 15-year rates run ~0.5% lower): the 30-year costs ~$1,799/month in principal and interest, totaling ~$647,600 over the loan’s life — $347,600 in interest. The 15-year costs ~$2,451/month, totaling ~$441,200 — only $141,200 in interest.
The difference: $206,400 in interest savings with the 15-year, and you own your home free and clear 15 years sooner — right when many buyers’ kids hit college age, making the timing doubly valuable. That’s life-changing money. But the 15-year demands $652/month more — $7,800/year — every month for 15 years, with no flexibility. Miss the math on affordability and the “better” loan becomes the one that causes a foreclosure. The CFPB’s mortgage calculators let you run your exact numbers.
When the 15-Year Wins
You’re buying below your means: If the 15-year payment is under 25% of take-home pay and you still save for retirement, the 15-year is a wealth-building machine — forced savings at a guaranteed return (your mortgage rate).
You’re refinancing mid-life: Refinancing a 30-year (with 22 years left) into a 15-year often barely raises the payment while shaving 7 years — the highest-ROI refinance move most homeowners can make.
You’re close to retirement: Entering retirement mortgage-free transforms your finances — no $1,800/month housing payment on a fixed income. If you’re 40–50 buying a home, the 15-year aligns payoff with retirement beautifully.
You’re disciplined but want forcing: Some people won’t invest the difference — they’ll spend it. The 15-year removes temptation by contract.
When the 30-Year Wins
Payment flexibility is survival: The 30-year’s lower required payment is an insurance policy — job loss, medical emergency, income dip — you can always pay more voluntarily, but you can’t pay less on a 15-year. Financial planners overwhelmingly favor flexibility for anyone without massive reserves.
You can beat the rate investing: If your mortgage is 6% and your 401(k) earns 8–10% long-term, every extra dollar toward the mortgage instead of retirement loses money mathematically. The 30-year frees cash for higher-return uses — but only if you actually invest it.
You’re stretching to buy: First-time buyers in expensive markets often need the 30-year’s lower payment just to qualify. A 15-year you can’t afford isn’t an option — it’s a fantasy.
Inflation erodes the debt: Fixed 30-year payments get cheaper in real terms over time as wages and prices rise — your $1,799 payment in year 25 feels much smaller than in year 1, while your home’s value and your income have grown around it. The 15-year captures less of this benefit because it’s gone before inflation does its best work.
The Hybrid: 30-Year Loan, 15-Year Behavior
The sophisticated answer for many: take the 30-year for flexibility, then pay it like a 15-year voluntarily. You get the lower required payment (safety net) plus accelerated payoff (wealth building) — and you can dial back to minimum payments during emergencies. One extra payment per year alone cuts a 30-year loan to ~22 years.
The catch: it requires discipline the 15-year enforces automatically. Automate the extra payment (biweekly payments = one extra payment yearly, painlessly — most servicers offer this) so willpower isn’t involved. This hybrid fails only when “voluntary” becomes “theoretical” — which is why automation, not intention, is the entire strategy. Check FHFA data on rate trends to time refinancing decisions wisely.
The Refinance Angle: You’re Not Locked In Forever
Here’s what the 15-vs-30 debate often misses: the choice isn’t permanent. Start with a 30-year for flexibility, then refinance into a 15-year when your income grows, rates drop, or you’ve built equity. This staged approach is how many wealthy homeowners actually do it — they don’t start with 15-year payments on a starter salary; they graduate into them.
The math of refinancing into a shorter term is powerful: after 5 years on a $300,000 30-year loan at 6%, you owe ~$279,000. Refinancing that balance into a 15-year at 5.5% costs ~$2,280/month — often close to your original payment if rates cooperated — while cutting total remaining interest dramatically. The key: refinance for term reduction, not just rate reduction. Too many homeowners refinance into another 30-year, resetting the clock and erasing years of progress.
Watch the costs: refinancing runs 2–5% of the loan in closing costs, so the breakeven must justify it. And never refinance into a longer term to “lower payments” unless it’s a genuine emergency strategy — it’s wealth destruction disguised as relief.
What About ARMs and Other Options?
Adjustable-rate mortgages (5/1, 7/1 ARMs) offer lower initial rates — worth considering if you’ll sell or refinance before adjustment. But in 2026’s rate environment, the ARM discount over fixed rates is modest, limiting the appeal. For most buyers, the real decision remains 15 vs. 30 fixed — the options with 30 years of data proving their outcomes.
Whichever you choose, the fundamentals matter more than the term: buy a home you can afford (not just qualify for), keep an emergency fund, and understand the full purchase — inspecting older homes and choosing the right agent affect your finances as much as the loan term.
Conclusion
The 15-year mortgage saves ~$200,000 in interest and builds wealth relentlessly — it’s better if you can comfortably afford the payment (under 25% of take-home pay), are refinancing mid-loan, or are racing toward a mortgage-free retirement. The 30-year offers crucial payment flexibility and frees cash for higher-return investing — it’s better if you need the safety net, are stretching to buy, or will actually invest the difference rather than spend it. The hybrid (30-year loan paid like a 15-year) gives you both — if you automate it. Run your numbers, be honest about your discipline, and choose accordingly.
Frequently Asked Questions
How much interest do I actually save with a 15-year vs 30-year mortgage?
On a $300,000 loan, roughly $200,000+ in interest savings, plus owning your home 15 years sooner. The trade-off is ~$650/month higher payments.
Is it really better to get a 15-year mortgage or invest the difference?
Mathematically, investing usually wins if returns exceed your mortgage rate — but only if you actually invest consistently. The 15-year wins on enforced discipline.
Can I actually pay a 30-year mortgage like a 15-year mortgage?
Yes — make the 15-year payment amount on your 30-year loan. You get flexibility (can drop to minimum anytime) with accelerated payoff. Automate it for discipline.
Do 15-year mortgages really have lower interest rates than 30-year loans?
Yes — typically ~0.5% lower than 30-year rates, which compounds the savings beyond just the shorter term.
What is the single biggest risk of choosing a 15-year mortgage?
Payment inflexibility — the higher required payment leaves less margin for job loss, emergencies, or income drops. Never stretch so far that the payment threatens your emergency fund.